Can You Do Cost Segregation on Residential Rental Property?
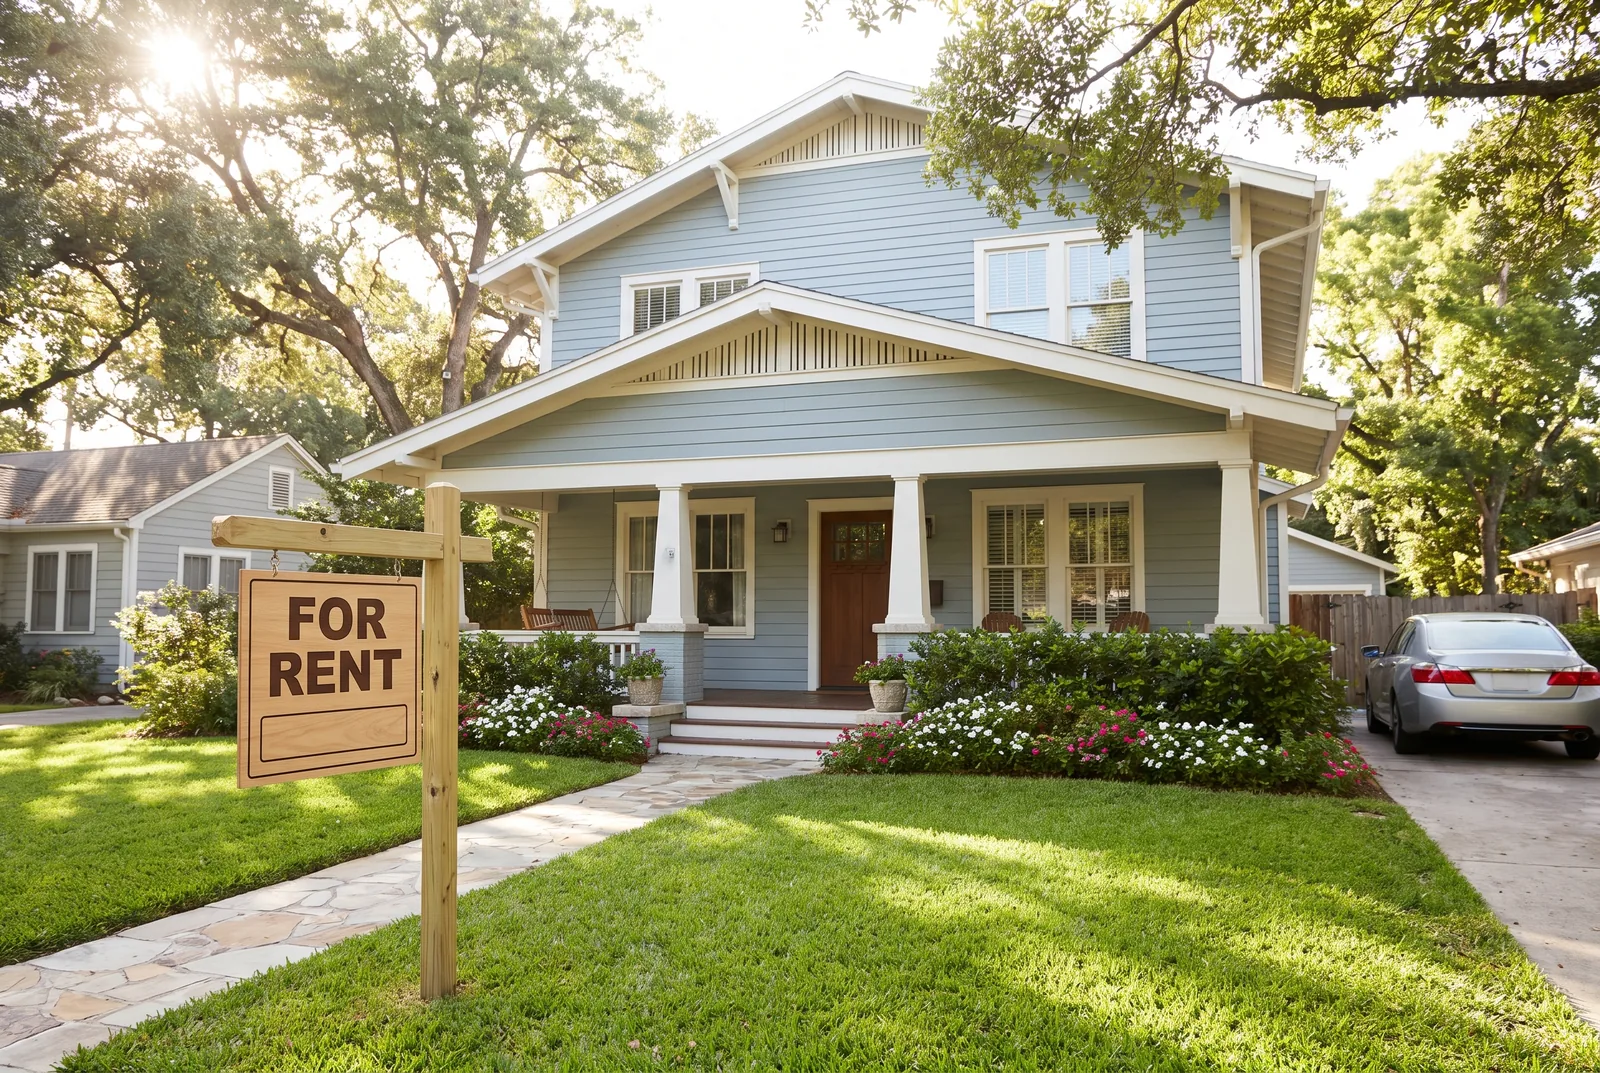
One of the most common questions investors ask is whether cost segregation is only for large commercial buildings or whether it works on a single-family rental or small multifamily too. The short version is that it absolutely works on residential rentals, and with 100% bonus depreciation restored for 2026 the first-year benefit can be substantial. The more useful question is not whether you can do it, but whether you should, because the payoff depends heavily on your tax situation and how you use the losses.
How residential rental depreciation normally works
When you buy a rental, the IRS makes you recover the building's cost through depreciation rather than deducting it all at once. Land does not depreciate. The structure is written off on a straight-line basis over 27.5 years for residential property. On a $300,000 building that is a little under $11,000 a year, a steady but modest deduction that ignores the fact that carpet, appliances, and a parking pad wear out far faster than the roof and foundation.
This slow schedule is the default the whole strategy improves on. The building shell genuinely does last decades, so 27.5 years is reasonable for the roof, framing, and foundation. The problem is that the IRS default lumps everything that is not land into that one long life, including items that plainly wear out in a fraction of the time. Cost segregation simply corrects that by matching each component to a recovery period that reflects its real economic life.
What a study actually reclassifies
A cost segregation study has an engineer identify the components of the property that qualify for shorter recovery periods and separate them from the 27.5-year building shell. On a typical residential rental that includes:
- 5-year property: appliances, carpet and other removable flooring, window treatments, and furniture in a furnished rental.
- 7-year property: certain fixtures and specialized equipment.
- 15-year land improvements: driveways, walkways, fencing, landscaping, and exterior lighting.
On most residential properties a study moves roughly 20% to 35% of the depreciable basis into these short-life buckets. Because the 2025 federal tax law permanently restored 100% bonus depreciation for qualifying property placed in service after January 19, 2025, those 5, 7, and 15-year items can be deducted in full in year one instead of over their recovery periods.
How much you can accelerate
Here is an illustrative single-family rental bought for $400,000, with $80,000 allocated to land and a $320,000 depreciable basis. Assume a study reclassifies 28%, or about $90,000, into short-life property.
| Approach | First-year depreciation |
|---|---|
| Straight-line, no study | ~$11,600 |
| Cost seg, short-life taken over 5 to 15 years | ~$30,000 |
| Cost seg + 100% bonus on short-life property | ~$98,000 |
The numbers scale with the building value and your allocation, so treat these as a model rather than a promise. A quick estimate is the fastest way to see a realistic range for your property.
The catch most investors miss: passive loss rules
Creating a big deduction is easy. Using it this year is the hard part. Long-term residential rentals are passive activities by default, which means the losses they generate can only offset passive income. If a cost seg study hands you a $98,000 loss but you have no passive income, that loss is suspended and carried forward. It is not lost, it releases when you have passive income or when you sell the property in a taxable sale, but it will not knock down your W-2 taxes this year. This is the single most common disappointment with cost segregation on residential rentals: the study works perfectly, the deduction is real, and yet a high-income W-2 owner sees no change on this year's return because the loss is trapped by Section 469. There are three main ways around that wall:
- The $25,000 special allowance. If you actively participate in the rental and your modified adjusted gross income is under $100,000, you can deduct up to $25,000 of rental losses against other income. That allowance phases out between $100,000 and $150,000 of MAGI and disappears above it.
- Real estate professional status. If you spend more than 750 hours in real property trades, with real estate making up more than half your working time, and you materially participate, your rentals become non-passive.
- The short-term rental route. If the average guest stay is seven days or fewer and you materially participate, the property is not treated as a passive rental at all. We cover that in detail in our guide to the short-term rental loophole.
One wording point trips people up. The $25,000 allowance requires "active" participation, a low bar that means making management decisions like approving tenants or arranging repairs. Real estate professional status and the short-term rental route require "material" participation, a higher bar measured in hours. They are not the same test, and confusing them is a frequent mistake. If none of the three exceptions fits your situation this year, the honest answer is that the study still has value, it just banks the loss for a future year rather than paying off immediately.
Furnished and multifamily rentals
Two property types tend to benefit more than a bare single-family house. A furnished rental adds appliances, furniture, and decor that are all short-life 5-year property, increasing the share of basis you can accelerate. Small multifamily, duplexes through small apartment buildings, carries more of the land improvements and specialized systems that fall into the 7 and 15-year buckets. In both cases the percentage of basis a study can reclassify tends to sit at the higher end of the 20% to 35% range, which improves the return on the study fee.
When cost segregation makes sense on a rental
- Higher building value. The more basis sits in the structure rather than land, the larger the benefit relative to the study fee.
- A way to use the loss. Passive income to offset, the $25,000 allowance, real estate professional status, or a qualifying short-term rental.
- A multi-year hold. Selling soon after accelerating depreciation can trigger recapture and erode the benefit.
- A recent purchase or build. You can even catch up missed depreciation on a property you have owned for years without amending old returns.
For a fuller decision framework, see when cost segregation makes sense.
What it costs and what to watch
An engineering-based study on a residential rental typically runs a few thousand dollars, far less than a large commercial study. The first-year benefit usually dwarfs that fee when you can actually use the loss. Two cautions apply. First, accelerated depreciation is recaptured when you sell, and the short-life personal property is generally recaptured at ordinary income rates. Second, the IRS favors a documented, engineering-based study over a back-of-the-envelope DIY estimate, which is a real audit risk. Because rental taxation is highly specific to your income and participation, confirm the plan with a CPA before you rely on it.
Frequently asked questions
Can you do cost segregation on residential rental property?
Yes. Single-family homes, duplexes, and small multifamily rentals all qualify. A study reclassifies parts of the building into 5, 7, and 15-year property so you can accelerate depreciation instead of spreading it over 27.5 years.
Is it worth it for a single-family rental?
It can be, especially on higher-value buildings held several years when you can actually use the loss. On a low-value property, or when passive loss rules suspend the deduction, the benefit may not justify the study fee.
Will the deduction lower my W-2 taxes?
Not automatically. Long-term rental losses are passive and offset only passive income unless you qualify for the $25,000 special allowance, hold real estate professional status, or run a qualifying short-term rental. Otherwise the loss is suspended and carried forward.
How much does a residential cost segregation study cost?
A residential study typically runs a few thousand dollars, far less than a large commercial study. The first-year benefit usually exceeds that fee when you can use the loss. See our guide on study cost for ranges.
Can I do cost segregation on a rental I bought years ago?
Yes. A look-back study lets you catch up the missed depreciation on your current return using a change in accounting method, without amending prior-year returns.
Estimate your tax savings
Get a quick read on your first-year benefit and match with a qualified provider.
Estimate my savingsThis is general educational information, not tax advice. Cost segregation and depreciation rules are complex and change; consult a qualified CPA or tax advisor before acting.